India’s biggest infrastructure financier plans to enter the country’s fast-growing asset-backed securities market, according to people familiar with the matter, as it seeks to diversify its funding sources and expand its investment portfolio.
The National Bank for Financing Infrastructure & Development, or NaBFID, created to help fund India’s development push, is preparing to participate in the wholesale ABS market next year, both as an issuer and an investor, the people said, asking not to be identified as the details are private.
The move would give the state-run lender a foothold in a rapidly expanding corner of India’s debt market, where global banks have been stepping up investments to gain exposure to the world’s fastest-growing major economy.
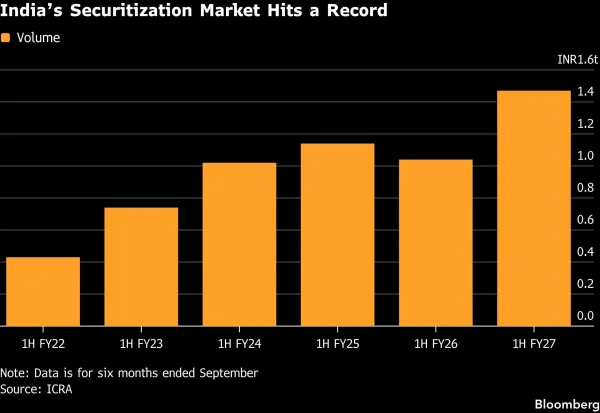
India’s securitization volume jumped nearly 42% to 1.47 trillion rupees ($15.7 billion) in the six months through September, the strongest first half on record, according to an October report by ICRA. The rating agency expects volume to reach as much as 2.7 trillion rupees in the fiscal year ending March 2027.
Read More: Global Banks Drive India Asset-Backed Securities Sales to Record
NaBFID is evaluating the strategy and structure for the proposed transactions, and details have yet to be finalized, the people said.
A representative at NaBFID did not reply to an email seeking comment.
Despite its rapid expansion, India’s securitization market remains small compared with those in the US and Europe. A narrow investor base dominated by banks and mutual
 Broadening funding sources for infrastructure is critical to India’s economic ambitions. The country may need as much as 770 trillion rupees for power, roads and railways and other infrastructure through 2047, when Prime Minister Narendra Modi’s government aims for the country to achieve developed economy status.
NaBFID was set up in 2021 to attract new capital into infrastructure, deepen the bond market and help narrow the sector’s financing gap.
The lender’s entry could also expand the ABS market beyond the retail loans that currently dominate securitized pools, including vehicles, gold and mortgage loans. ABS bundle loans or other income-producing assets into tradable debt instruments, allowing investors to gain exposure to the underlying cash flows.
India’s securitizations generally take two forms: One relates to securities locally known as pass-through certificates or PTCs which are issued against pools of underlying assets. The other known as direct assignments, typically involve the bilateral sale of a pool of loans from one financial institution to another.
NaBFID plans to initially issue pass-through certificates before investing in similar securities issued by other institutions the people said.
Reliance Industries Ltd., India’s largest conglomerate, recently tapped the market through PTCs in one of the biggest such local transactions this year.
The National Bank for Financing Infrastructure & Development, or NaBFID, created to help fund India’s development push, is preparing to participate in the wholesale ABS market next year, both as an issuer and an investor, the people said, asking not to be identified as the details are private.
The move would give the state-run lender a foothold in a rapidly expanding corner of India’s debt market, where global banks have been stepping up investments to gain exposure to the world’s fastest-growing major economy.
India’s securitization volume jumped nearly 42% to 1.47 trillion rupees ($15.7 billion) in the six months through September, the strongest first half on record, according to an October report by ICRA. The rating agency expects volume to reach as much as 2.7 trillion rupees in the fiscal year ending March 2027.
Read More: Global Banks Drive India Asset-Backed Securities Sales to Record
NaBFID is evaluating the strategy and structure for the proposed transactions, and details have yet to be finalized, the people said.
A representative at NaBFID did not reply to an email seeking comment.
Despite its rapid expansion, India’s securitization market remains small compared with those in the US and Europe. A narrow investor base dominated by banks and mutual
NaBFID was set up in 2021 to attract new capital into infrastructure, deepen the bond market and help narrow the sector’s financing gap.
The lender’s entry could also expand the ABS market beyond the retail loans that currently dominate securitized pools, including vehicles, gold and mortgage loans. ABS bundle loans or other income-producing assets into tradable debt instruments, allowing investors to gain exposure to the underlying cash flows.
India’s securitizations generally take two forms: One relates to securities locally known as pass-through certificates or PTCs which are issued against pools of underlying assets. The other known as direct assignments, typically involve the bilateral sale of a pool of loans from one financial institution to another.
NaBFID plans to initially issue pass-through certificates before investing in similar securities issued by other institutions the people said.
Reliance Industries Ltd., India’s largest conglomerate, recently tapped the market through PTCs in one of the biggest such local transactions this year.